
U.S. institutional investors see room for markets to climb in 2027 and remain confident in AI’s long-term growth potential, but some of the biggest challenges to the technology’s expansion may lie beyond Wall Street. According to the Natixis Investment Managers 2027 Institutional Outlook Survey, 63% expect the S&P 500 to finish 2027 at an all-time high, while 84% believe AI investment still has a long runway for growth.
This press release features multimedia. View the full release here: https://www.businesswire.com/news/home/20261118114328/en/
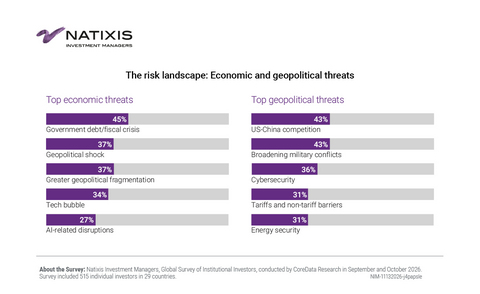
The risk landscape: Economic and geopolitical threats
That optimism comes with growing recognition of AI’s vulnerabilities. While 60% expect AI capital expenditures to continue driving markets, 70% believe the technology will fall short of delivering all the productivity gains currently priced into markets. Meanwhile, geopolitical competition, regulatory pressures and infrastructure constraints are raising questions about how smoothly AI’s investment potential will translate into broader economic growth.
The Natixis IM 2027 Institutional Outlook Survey captures the views of 515 institutional investors worldwide, including 80 U.S. respondents responsible for more than $76 billion in assets on average. The findings offer insight into how institutional investors are assessing market opportunities, economic risks and portfolio allocation decisions heading into 2027.
“Investors still see tremendous potential in AI, but 2027 could be a defining year for separating investment expectations from economic reality,” said Dave Goodsell, Executive Director at Natixis Investment Managers’ Center for Investor Insight. “The question is not just how much capital will flow into AI, but whether the technology can deliver the productivity gains markets are counting on amid growing geopolitical tensions and real-world constraints. Against that backdrop, institutions aren’t abandoning growth opportunities, but they’re becoming more selective about where they take risk and how they build their portfolios.”
AI’s growth runway faces real-world roadblocks
Despite elevated valuations and investment concentration, U.S. institutions remain optimistic about AI’s growth potential. While 39% believe AI is a bubble, 65% expect productivity gains from the technology to begin contributing to market growth in 2027.
Yet the industry’s rapid expansion brings new vulnerabilities. Six in ten (60%) believe a slowdown in AI capital expenditures could upend economic growth, underscoring the potential consequences of markets’ growing dependence on the technology. At the same time, 55% believe a significant new AI technology development could bring concentration risk to the forefront of equity markets.
Some of the greatest obstacles may emerge outside financial markets:
- Geopolitical competition: 81% expect the AI race to reignite tensions between the U.S. and China, and 76% believe AI will introduce new geopolitical risks for investors.
- Infrastructure constraints: 70% believe local opposition to data centers threatens the broader AI buildout.
- Regulatory backlash: 68% expect rising public resistance to AI to force government action.
Geopolitical uncertainty and fiscal pressures cloud the outlook
Beyond AI, institutions face an increasingly complex global risk landscape. Three-quarters (75%) believe political dysfunction in major markets is a growing threat to market stability, while 66% expect geopolitical conflicts to have meaningful impacts on markets in 2027.
When asked to identify their three greatest economic threats, U.S. institutions most frequently cited a government debt or fiscal crisis (44%), geopolitical shock (43%) and a technology bubble (39%).
Economic pressures are adding to the uncertainty. Nearly two-thirds (63%) believe reinflation will prove persistent, while 58% say slow growth is the new normal and 53% are increasingly concerned about stagflation. In addition, 64% believe rising energy prices could push vulnerable economies into recession.
Monetary policy remains a critical consideration. Nearly two-thirds (65%) expect Federal Reserve policy to matter more to markets than the results of the U.S. midterm elections, highlighting the continuing importance of the Fed’s decisions as investors balance inflation risks against signs of weakening growth.
Institutions balance growth opportunities with greater scrutiny
Despite mounting risks, U.S. institutions remain focused on capturing growth, but their investment outlook reveals a more selective approach across asset classes. Three-quarters (75%) expect an alternatives-diversified 60/20/20 portfolio to outperform the traditional 60/40 allocation in 2027, reinforcing the role of alternatives alongside traditional stocks and bonds.
The findings reveal a more nuanced approach to positioning portfolios:
-
Equities: Bullish, but selective. While 68% are bullish on stocks and 73% expect U.S. markets to outperform Europe, over half anticipate rising equity volatility, and only 21% plan to increase U.S. equity allocations. Conviction is strongest in defense stocks (79%), while energy (58%) and healthcare (55%) lead expectations for sector outperformance.
- Fixed income: Quality over yield. Just 35% are bullish on bonds, with institutions more likely to increase exposure to investment-grade corporate debt (35%) than high-yield bonds (19%). Meanwhile, 61% believe active management is essential in fixed income investing.
- Alternatives: Opportunity meets scrutiny. While 58% believe private markets continue to offer greater return potential than public markets, 71% have increased scrutiny and due diligence amid concerns about deal quality. Two-thirds (66%) see private equity secondaries as a source of attractive returns beyond liquidity.
Looking further ahead, 44% anticipate increasing private market allocations over the next 10 to 15 years. Together, the findings suggest institutions are maintaining their appetite for growth while becoming more discerning about where they take risk and how they manage portfolio exposures.
View and download a full copy of the report: https://www.im.natixis.com/en-us/insights/investor-sentiment/2026/institutional-outlook-2027
Methodology
The Natixis Investment Managers 2027 Institutional Outlook Survey was conducted by CoreData Research in September and October 2026 among 515 institutional investors across 29 countries, including 80 U.S. respondents collectively responsible for more than $6 trillion in assets.
About the Natixis Center for Investor Insight
The Natixis Center for Investor Insight is a global research initiative focused on the critical issues shaping today’s investment landscape. The Center examines sentiment and behavior, market outlooks and trends, and risk perceptions of institutional investors, financial professionals and individuals around the world. Our goal is to fuel a more substantive discussion of issues with a 360° view of markets and insightful analysis of investment trends.
About Natixis Investment Managers
Natixis Investment Managers’ multi-affiliate approach connects clients to the independent thinking and focused expertise of more than 15 active managers. Ranked among the world’s largest asset managers1 with nearly $1.5 trillion assets under management2 (€1.3 trillion), Natixis Investment Managers specializes in high-conviction active investment strategies, insurance and pension solutions, and private assets, and delivers a diverse offering across asset classes, styles, and vehicles. The firm partners with clients in order to understand their unique needs and provide insights and investment solutions tailored to their long-term goals.
Headquartered in Paris and Boston, Natixis Investment Managers is part of Groupe BPCE, the second-largest banking group in France through the Banque Populaire and Caisse d’Epargne retail networks. Natixis Investment Managers’ affiliated investment management firms include AEW; DNCA Investments;3 Flexstone Partners; Gateway Investment Advisers; Harris | Oakmark; Investors Mutual Limited; Loomis, Sayles & Company; Mirova; Naxicap Partners; Ossiam; Ostrum Asset Management; Seventure Partners; Vauban Infrastructure Partners; Vaughan Nelson Investment Management; VEGA Investment Solutions and WCM Investment Management. Additionally, investment solutions are offered through Natixis Investment Managers Solutions and Natixis Advisors, LLC. Not all offerings are available in all jurisdictions. For additional information, please visit Natixis Investment Managers’ website at im.natixis.com | LinkedIn: linkedin.com/company/natixis-investment-managers.
Natixis Investment Managers’ distribution and service groups include Natixis Distribution, LLC, a limited purpose broker-dealer and the distributor of various US registered investment companies for which advisory services are provided by affiliated firms of Natixis Investment Managers, Natixis Investment Managers International (France), and their affiliated distribution and service entities in Europe and Asia.
1 Survey respondents and publicly available data ranked by Investment & Pensions Europe/Top 500 Asset Managers 2026 ranked Natixis Investment Managers among the top 25 largest asset managers in the world based on assets under management as of December 31, 2025.
2 Assets under management (AUM) of affiliated entities measured as of September 30, 2026, are $1,495.7 billion (€1,316.8 billion). AUM, as reported, may include notional assets, assets serviced, gross assets, assets of minority-owned affiliated entities and other types of nonregulatory AUM managed or serviced by firms affiliated with Natixis Investment Managers.
3 A brand of DNCA Finance.
All investing involves risk, including the risk of loss. Investment risk exists with equity, fixed-income, and alternative investments. There is no assurance that any investment will meet its performance objectives or that losses will be avoided.
The views and opinions expressed may change based on market and other conditions. This material is provided for informational purposes only and should not be construed as investment advice. There can be no assurance that developments will transpire as forecasted. Actual results may vary.
NIM-11162026-lkokmhnv
View source version on businesswire.com: https://www.businesswire.com/news/home/20261118114328/en/
Media gallery



